Roof insurance claims, done right: documented, legal, paid properly.
Hail or wind hit your roof? Get a free inspection with 75–150 photos and a written Hunter-Gatherer Report™ before anyone files anything. We meet your adjuster, scope the job to code, and never play games with your deductible — because in Texas that's the law, and because we'll still be here next year.
Photos, a written Roof Grade and a clear next step.
Considering replacement? Explore sample prices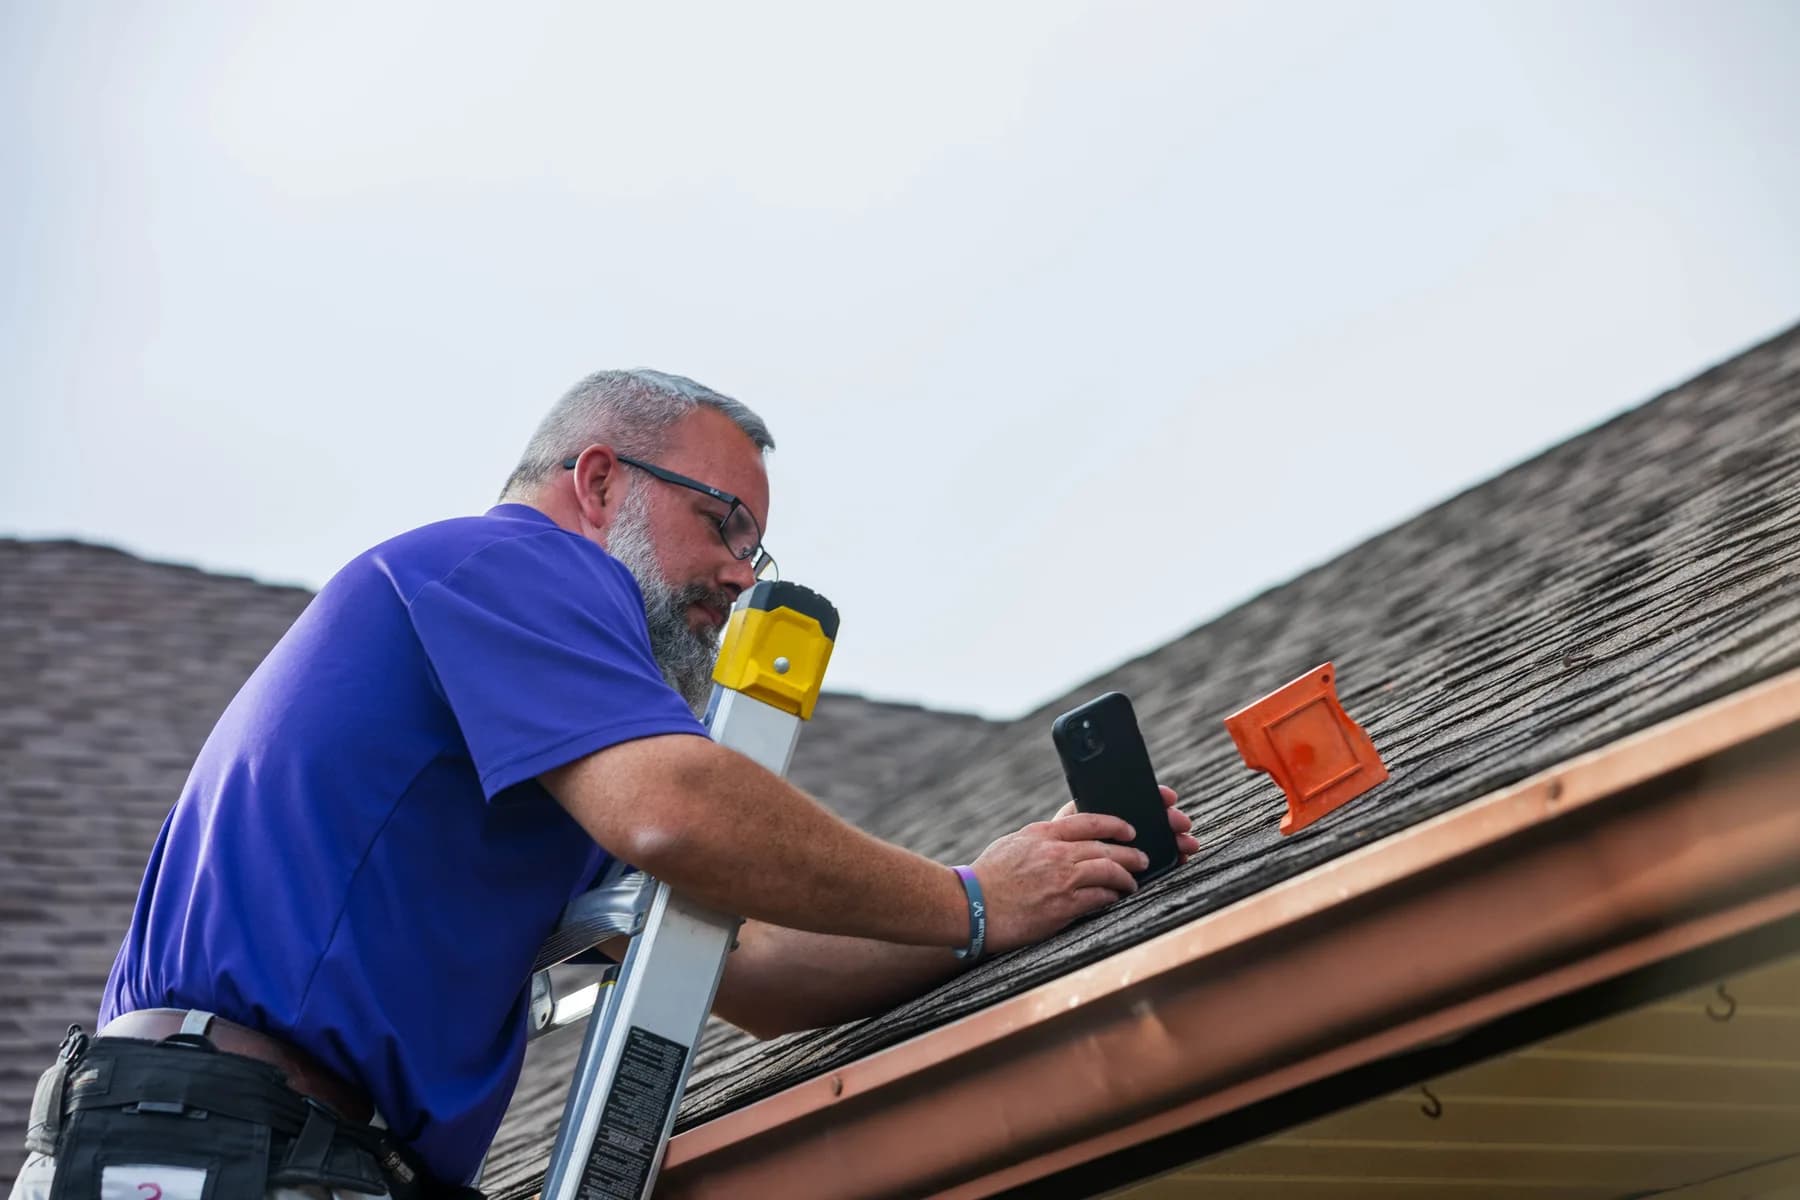 Photographed. Explained. Put in writing.


What to do before the storm chasers knock.
The week after a hailstorm is when the worst decisions get made — usually on the doorstep, with a stranger holding a clipboard. Do these six things instead.
Two checks, one deductible, no surprises.
Most homeowners have never filed a roof claim. Here is the whole process, in the order it happens, with who does what.
Free inspection + Hunter-Gatherer Report™
Every slope test-squared, the attic checked, 75–150 photos. You get the report whether or not there's a claim.
You file the claim
With your insurer, with our report attached. We give you the date of loss, the storm data and the photo set.
Adjuster meeting — we're there
We meet the adjuster on your roof, walk the damage together, and agree scope, code-required items and pricing on the spot.
First check: actual cash value
The insurer pays the depreciated value of the roof, minus your deductible. The estimate lists everything, including what's held back.
The build
Materials on site, the Monumental Installation System, SafeSite protection, the 26-point post-install inspection, SweepCheck clean-up. Code upgrades and supplements documented as we go.
Second check: recoverable depreciation
We send the completion certificate and final invoice; the insurer releases the held-back depreciation. You pay your deductible plus any upgrades you chose. That's it.
No, a roofer cannot waive your deductible in Texas.
Since September 1, 2019 it has been a criminal offense in Texas for a contractor to pay, waive, absorb, rebate or otherwise cover a homeowner's insurance deductible (Business and Commerce Code §27.02), the policyholder is required to pay it (Insurance Code chapter 707), and your insurer can ask for proof you paid it. We will never offer it, and you should walk away from anyone who does.
The deductible guide explains the percentage deductible, where it sits in the claim and the legal ways to make it easier.
Walk into your claim with 112 photos and a scored report.
Attic first. Every slope. A written answer you can understand, with the photos to back it up.
Free inspection + photo report + measurement + proposal — yours to keep.
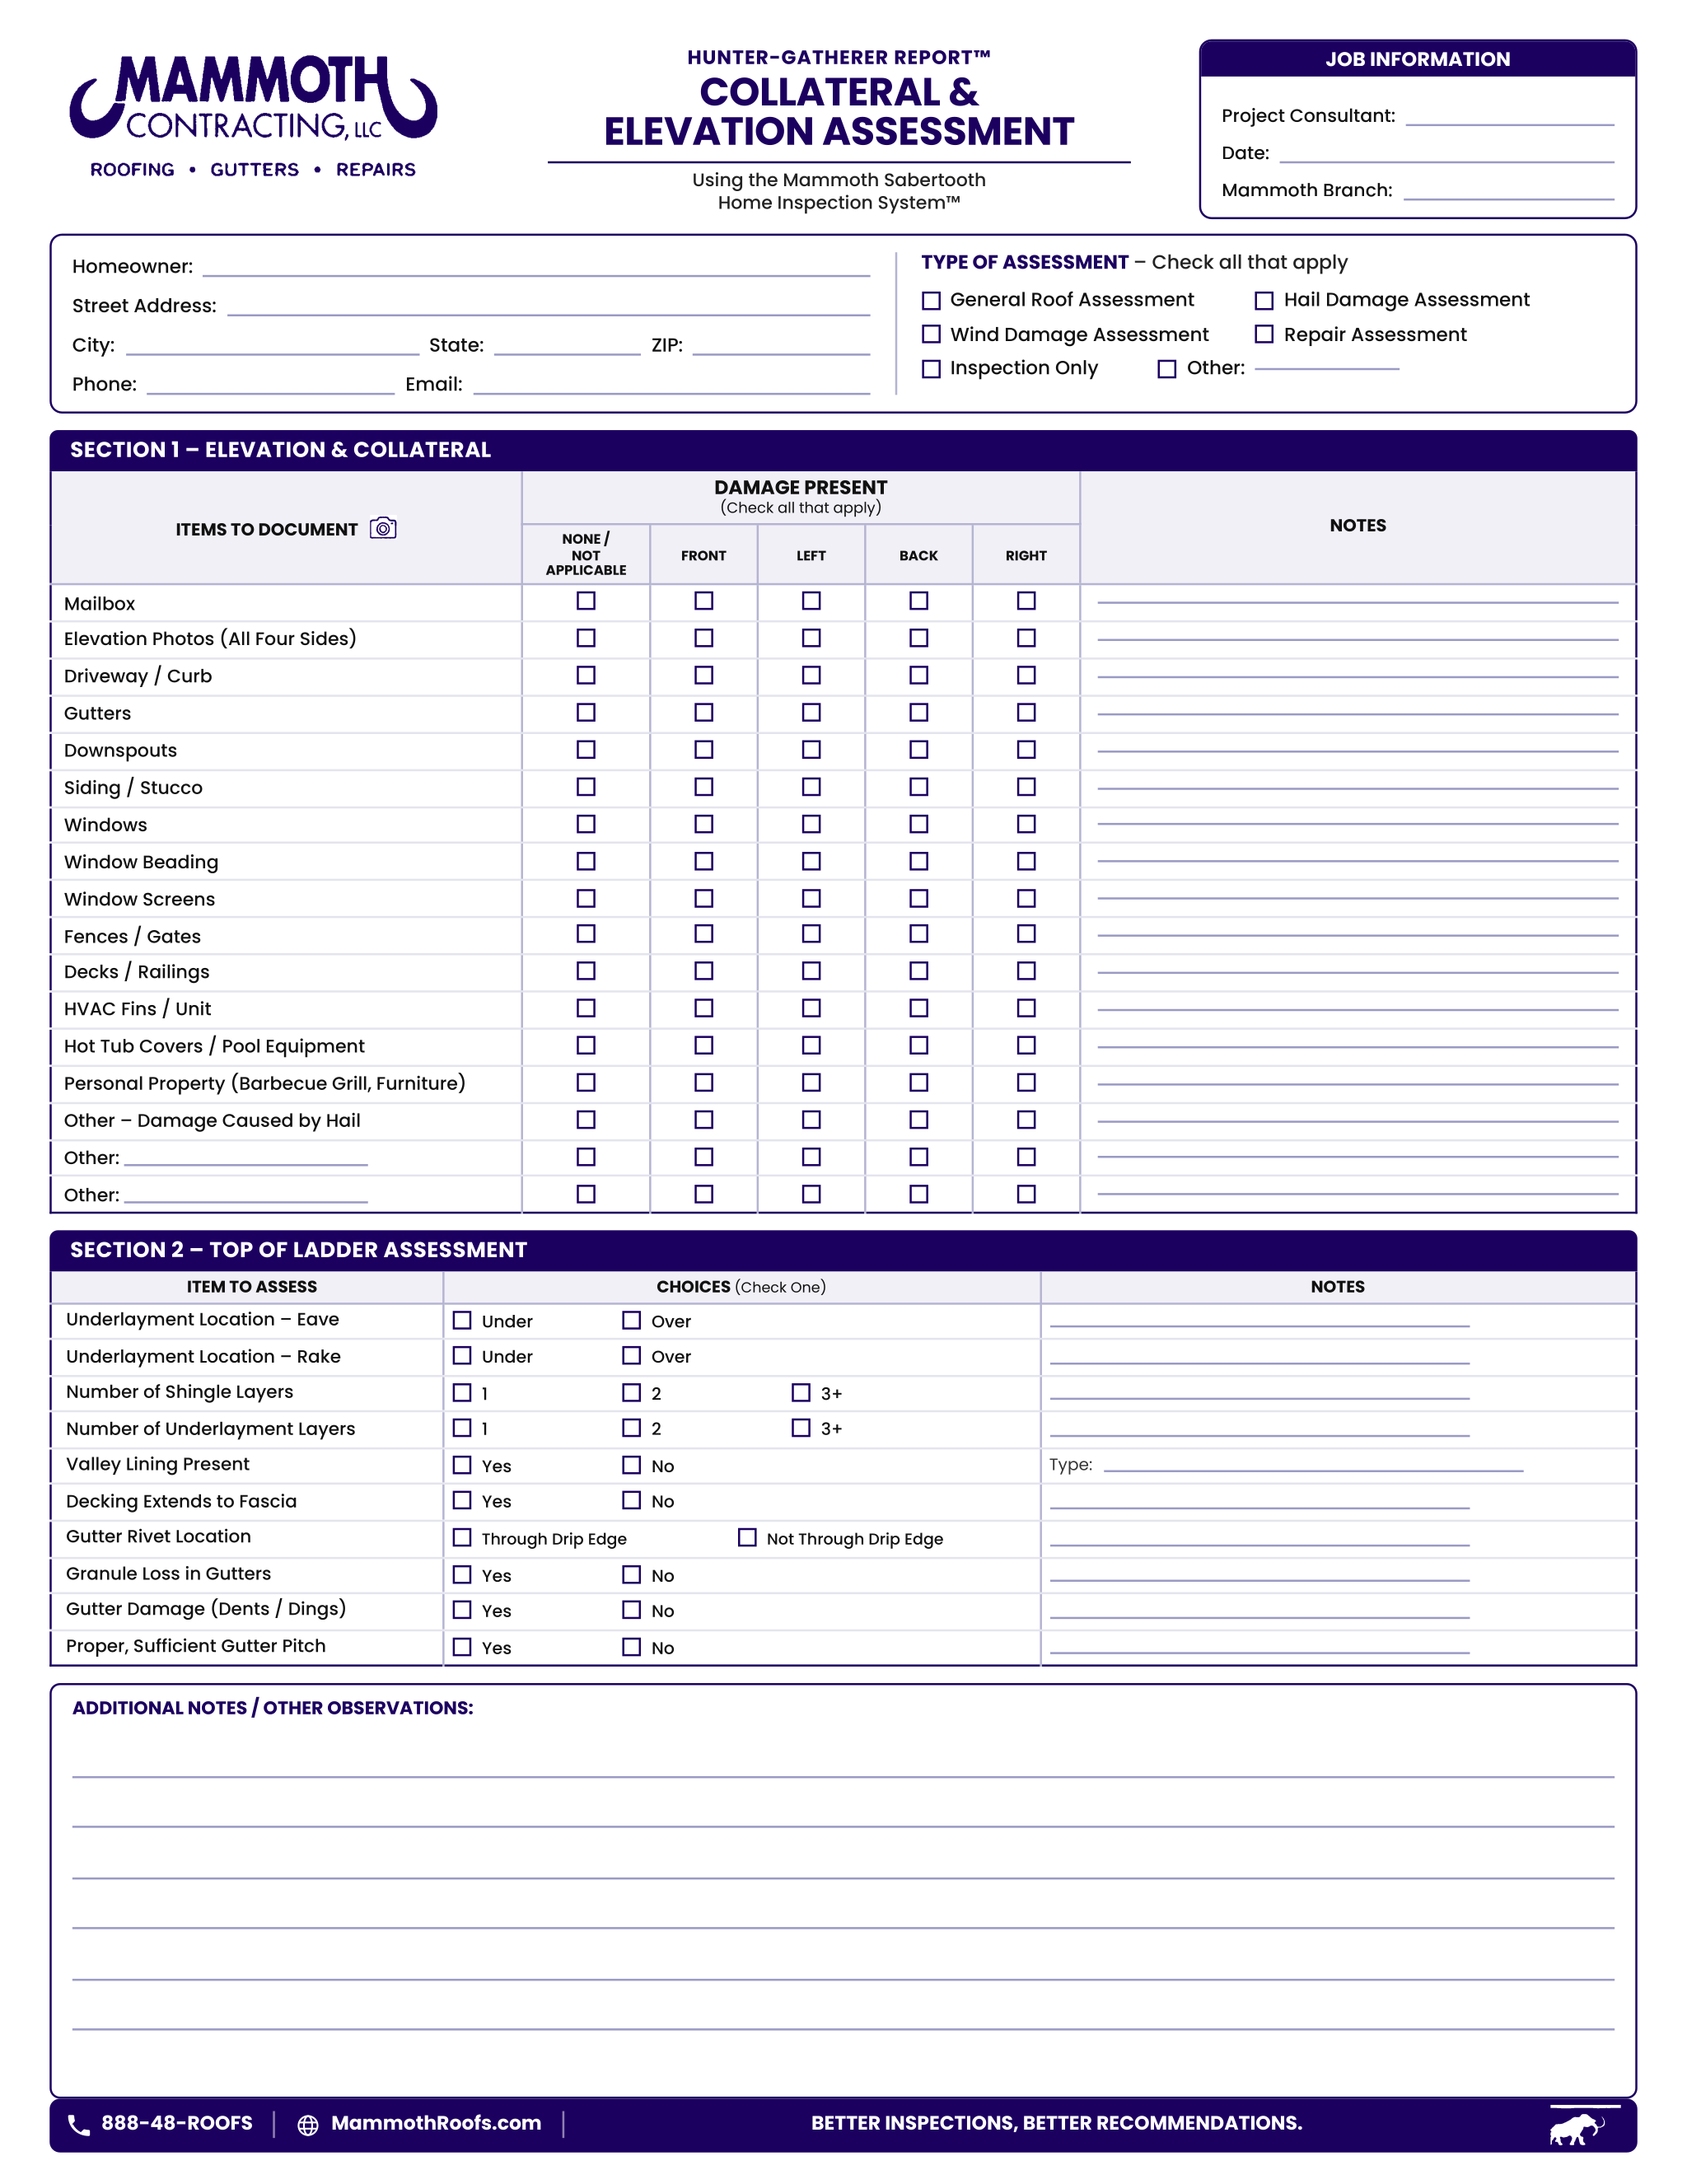
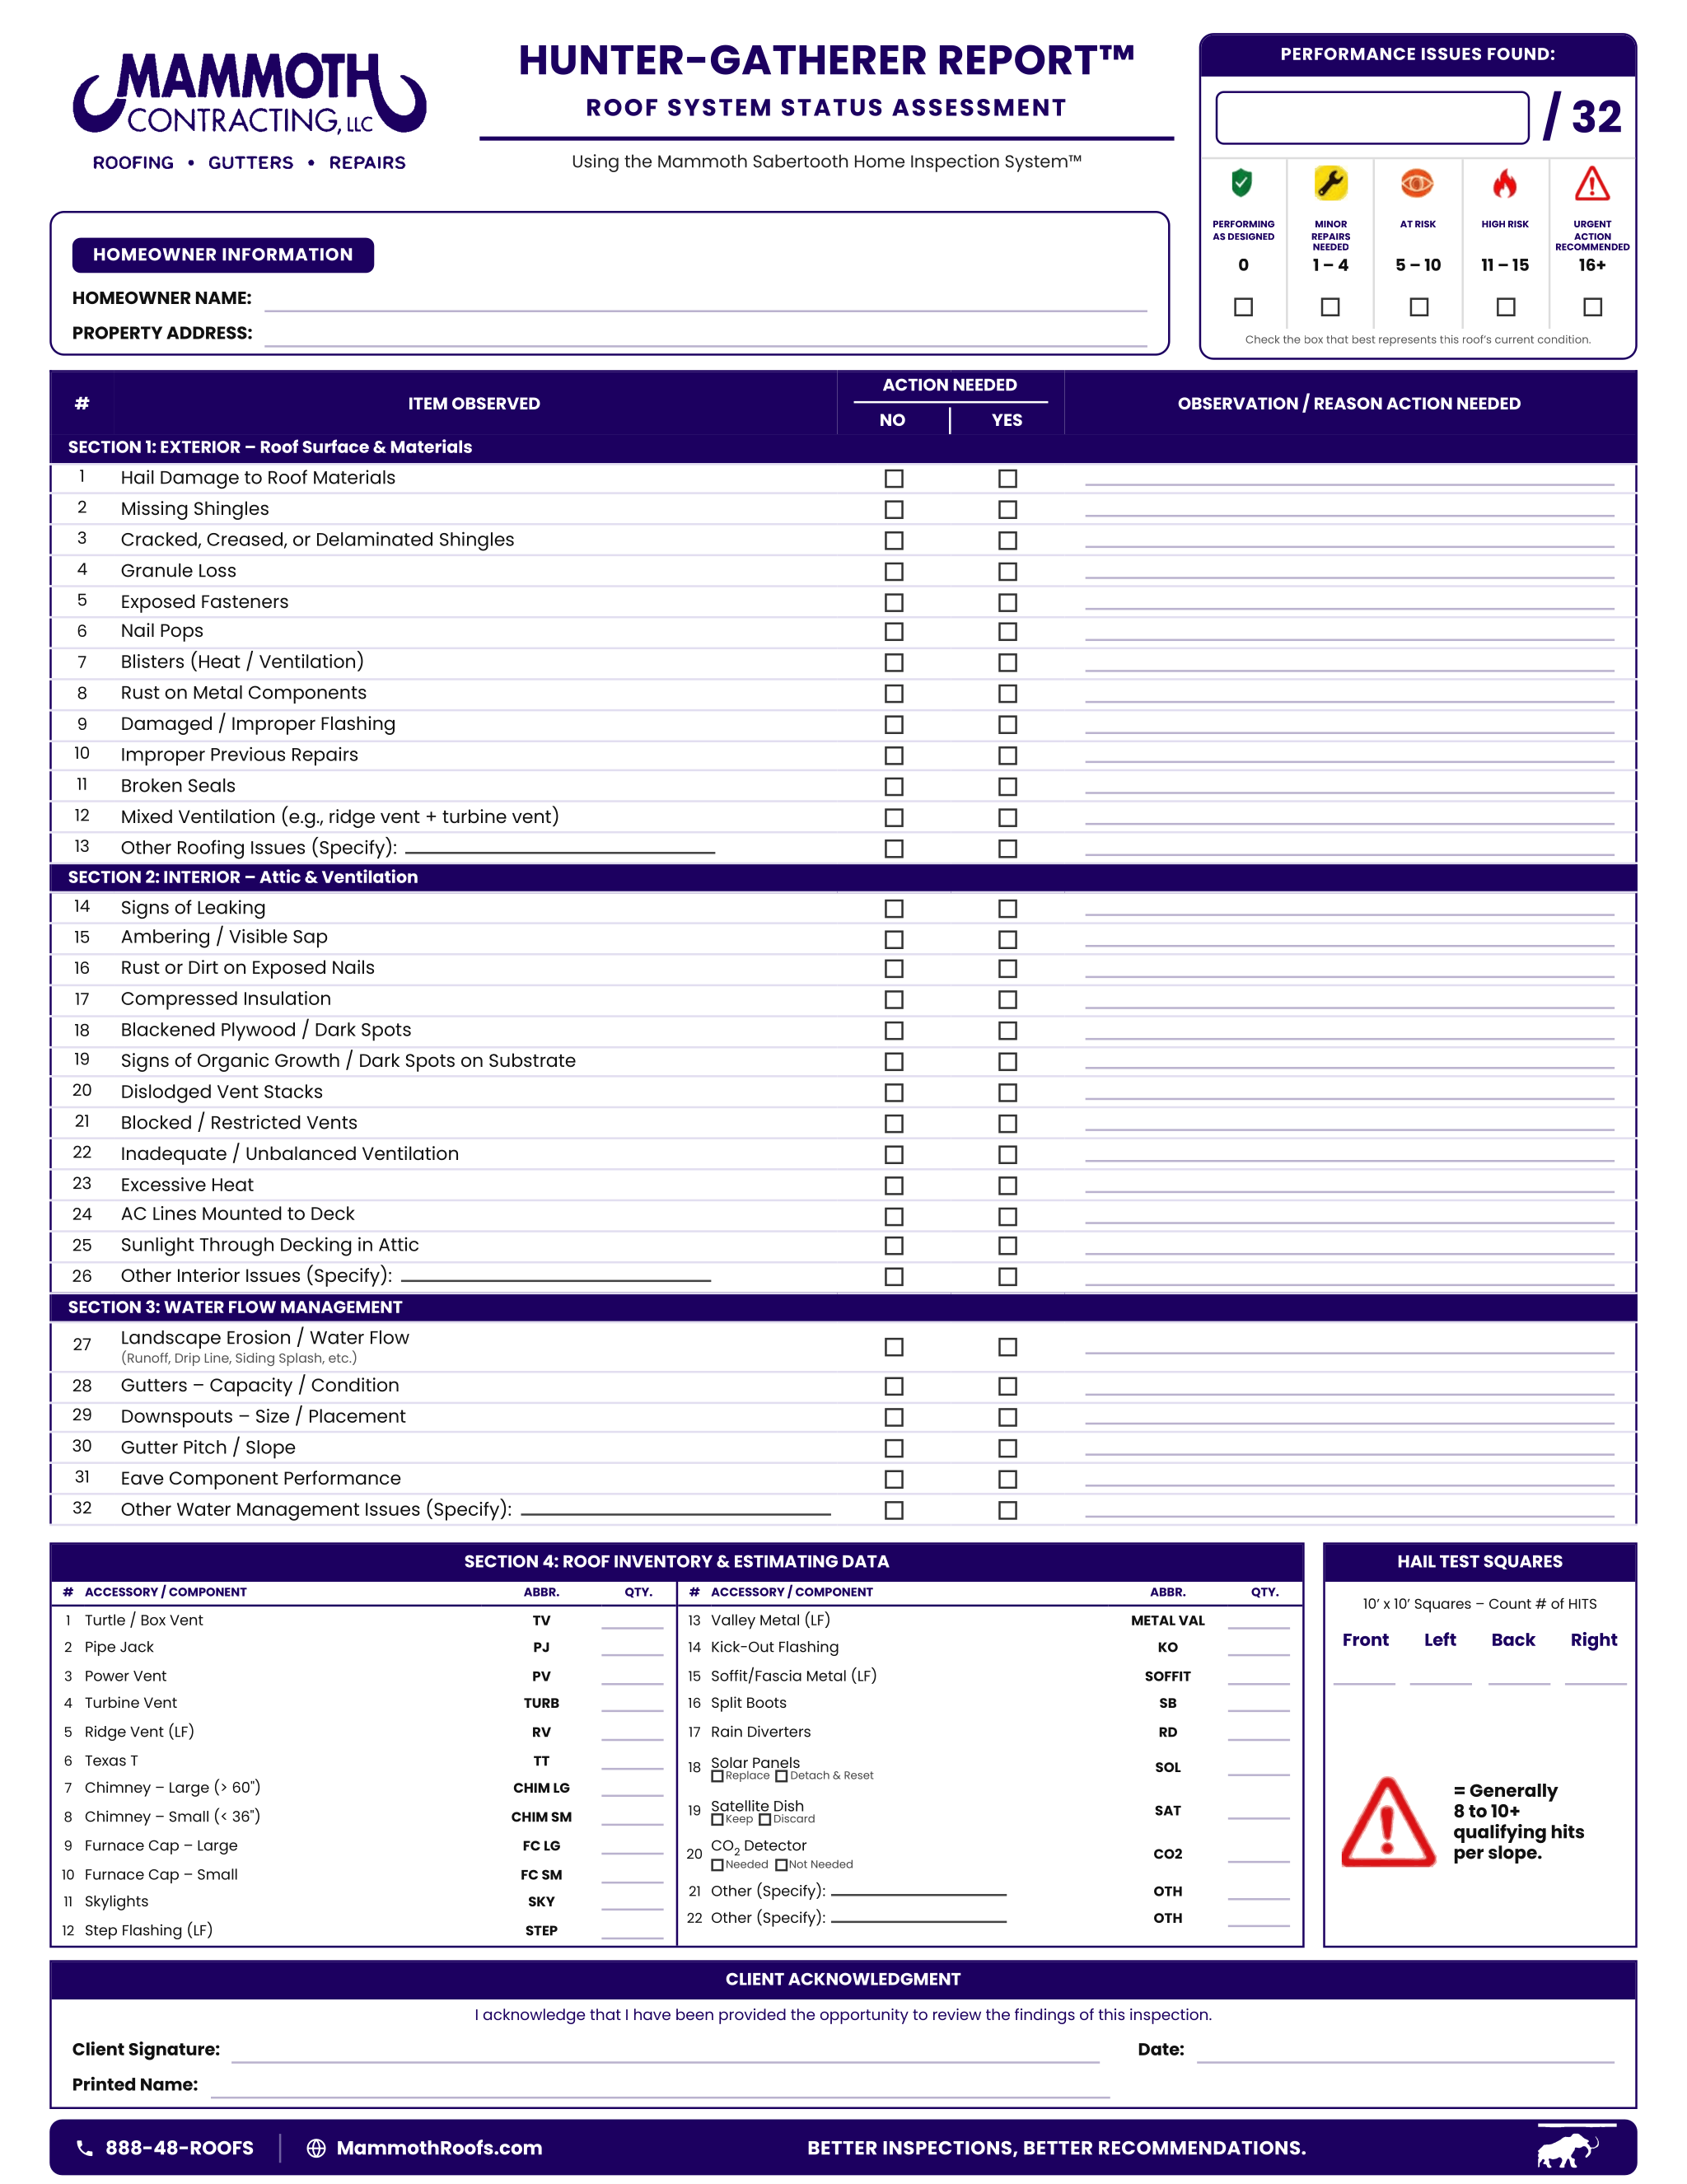
Hunter-Gatherer Report
A couple of repairs. Years of life left.
2 of 32 points need action: Minor repairs needed, Grade B
Sample report · your roof gets its own grade
01 / 03See all 32 points on the report
- 32 points inspected, starting in the attic
- 75–150 photos of what we find
- An A–F Roof Grade, scored in writing
- Inspection + photo report + measurement + proposal, yours to keep
Exterior: Roof Surface & Materials
- Hail Damage to Roof Materials
- Missing Shingles
- Cracked, Creased, or Delaminated Shingles
- Granule Loss
- Exposed Fasteners
- Nail Pops
- Blisters (Heat / Ventilation)
- Rust on Metal Components
- Damaged / Improper Flashing
- Improper Previous Repairs
- Broken Seals
- Mixed Ventilation (e.g., ridge vent + turbine vent)
- Other Roofing Issues (Specify)
Interior: Attic & Ventilation
- Signs of Leaking
- Ambering / Visible Sap
- Rust or Dirt on Exposed Nails
- Compressed Insulation
- Blackened Plywood / Dark Spots
- Signs of Organic Growth / Dark Spots on Substrate
- Dislodged Vent Stacks
- Blocked / Restricted Vents
- Inadequate / Unbalanced Ventilation
- Excessive Heat
- AC Lines Mounted to Deck
- Sunlight Through Decking in Attic
- Other Interior Issues (Specify)
Water Flow Management
- Landscape Erosion / Water Flow (Runoff, Drip Line, Siding Splash, etc.)
- Gutters – Capacity / Condition
- Downspouts – Size / Placement
- Gutter Pitch / Slope
- Eave Component Performance
- Other Water Management Issues (Specify)
Every point gets a yes or a no for action needed, with the reason written beside it. Page two records damage around the house (gutters, siding, windows, screens, fences, the AC unit) and what the inspector finds at the top of the ladder.
The honest answers, before you call your insurer.
Ask your local teamShould I file a claim at all?
Only if the damage justifies it. A denied claim still counts against you. That's why the inspection comes first — if the roof grades a B, we'll say so and you keep your claims history clean.
Will my premium go up?
Weather claims are treated differently from negligence claims, but every insurer is different. We can't promise what your carrier will do — we can make sure the claim is documented so it's paid properly the first time.
Do you deal with the insurance company for me?
We meet the adjuster, provide the documentation and communicate scope, code and pricing. We are roofers, not public adjusters or lawyers — if a claim needs those, we'll tell you.
What if the estimate is lower than the real cost?
We document the difference and submit a supplement with photos and code references. Legitimate items usually get paid. Items that aren't legitimate, we don't ask for.
Can you help if I'm not in San Antonio?
Yes. Mammoth has offices in Boerne, Temple and Garland, and local teams for Austin and Round Rock and for Kerrville and Marble Falls. Every market gets the same free inspection and the same written process.
Know where
your roof stands.
The Roof Grade is free. The report is written.
What happens next is your decision.
- 32 inspection points, attic first
- 75–150 photos of what we find
- An honest, written recommendation